Compulsory Insurance in Vietnam
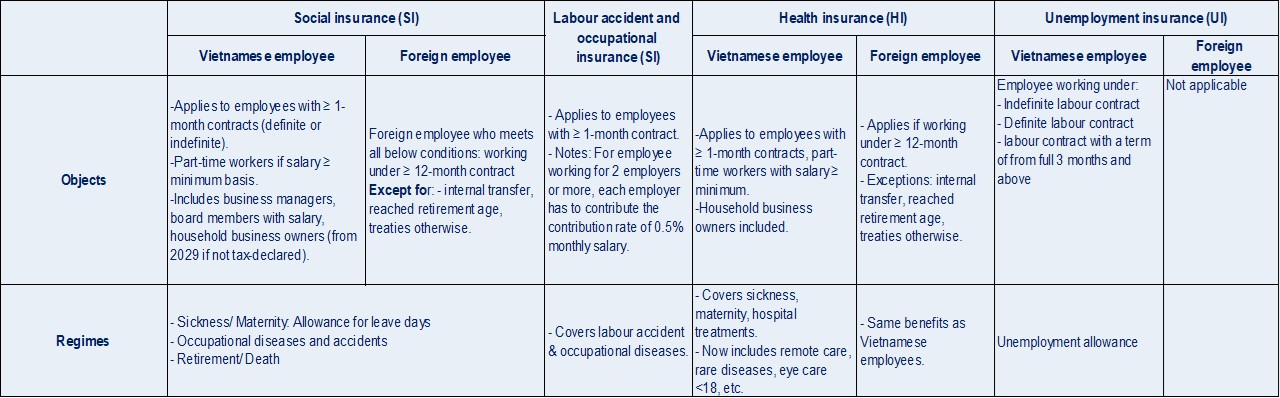
Compulsory Insurance for Vietnamese
| Item | Capped Salary for Contribution | Employee Contribution Rate | Employer Contribution Rate |
| Social Insurance (SI) | 20 times of common minimum wage | 8% | 17.50% |
| Health Insurance (HI) | 20 times of common minimum wage | 1.5% | 3% |
| Unemployment Insurance (UI) | 20 times of regional common minimum wage* | 1% | 1% |
- Common minimum wage for SI/HI contribution purpose: from 1 Jul 2024: VND2,340,000
- Capped salary for SI/HI contribution: from 1 Jul 2024: VND46,800,000
Regional minimum basic salary for UI contribution purpose:
| Region | Current Minimum Wage (VND) | Current Capped Salary for Contribution (VND) |
| I | 4,960,000 | 99,200,000 |
| II | 4,410,000 | 88,200,000 |
| III | 3,860,000 | 77,200,000 |
| IV | 3,450,000 | 69,000,000 |
The salary cap for statutory unemployment insurance contributions will be adjusted as follows from 1 January 2026:
| Region | Minimum Wage (VND) from 1 January 2026 | Current Capped Salary for Contribution (VND) from 1 January 2026 |
| I | 5,310,000 | 106,200,000 |
| II | 4,730,000 | 94,600,000 |
| III | 4,140,000 | 82,800,000 |
| IV | 3,700,000 | 74,000,000 |
- Employers are advised to review and update their labour contracts, collective agreements, and internal policies to ensure compliance with the new minimum wage levels.
- Any existing terms or benefits that are more favorable to employees should remain unchanged.
Compulsory Insurance for Foreign Employees
| Item | Capped Salary for Contribution | Employee Contribution Rate | Employer Contribution Rate |
| Social Insurance (SI) | 46.800.000 VND | 8% | 17.5% |
| Health Insurance (HI) | 46.800.000 VND | 1.5% | 3% |
| Unemployment Insurance (UI) | Not applicable | 0% | 0% |
- Common minimum wage for SI/HI contribution purpose: from 1 Jul 2023: VND2,340,000
- Capped salary for SI/HI contribution: from 1 Jul 2024: VND46,800,000
Notes:
- Part-time employees → Must still pay mandatory social insurance (even if not paid for 14+ days in a month).
- Exemptions (no contribution for that month unless agreed otherwise):
- Employees with contracts ≥ 1 month who do not receive salary for 14+ days.
- Managers receiving salaries.
- Foreign employees in the same situation.
- Not subject to social insurance at all:
- Employees on probationary contracts.
- Part-time employees earning below minimum salary base.
- Employees on fixed-term (≥1 month) or indefinite contracts but earning below the threshold.
Salary Used As The Basis For Compulsory Insurance Contribution:
The monthly salary used as the basis for social insurance contributions includes:
Salary components:
- Based on job position/title
- Allowances for working conditions, job complexity, living conditions, labour attraction (must be fixed & agreed in contract)
- Other fixed allowances agreed in contract, paid regularly (excluding performance/productivity-based allowances)
Managers without salary & household business owners:
- Can choose their salary as contribution basis
- Range: minimum = reference level, maximum = 20 × reference level
- After 12 months → can reselect salary
Contribution rules:
- Salary basis must be between reference level and 20 × reference level
- Until base salary is abolished → reference = base salary
- After abolition → reference level cannot be lower than base salary
Social Insurance Contribution Rules
Contribution Rules for Managers (No Salary) & Household Business Owners
Contribution rates:
- 3% → Sickness & maternity fund
- 22% → Retirement & death fund
Payment methods & deadlines:
- Pay via household business/enterprise/cooperative/union
- Options: monthly, quarterly, or semi-annual
- Deadline: Last day of the month following the contribution cycle
Other rules:
- Late payment → 0.03% daily interest
- Foreign currency → converted to VND at official exchange rate (fixed on Jan 2 & Jul 1 each year; next working day if holiday)
Late Payment Deadlines (Employers)
- Monthly contributions → Due by last day of the following month.
- Quarterly or semi-annual contributions → Due by last day of the month after the cycle ends.
Late / Evasion of Social Insurance Contributions
Delayed Payment:
Non-payment/underpayment → beyond due date (≤60 days)Failure to register employees → within 60 days after due period
Evasion:
- Not registering or underreporting salary basis
- Non-payment/underpayment >60 days, even after notice
- Other cases per government regulations
- Exceptions: Certain legitimate reasons (per Law 2024)
Penalties & Enforcement:
- Full overdue + 0.03% daily interest
- Administrative sanctions, no award eligibility
- If unpaid/incomplete by June 30, 2025 → treated as late payment & evasion under law
We Provide Expertise on Work Visa Applications!
Our professional team of 200+ has years of experience dealing with local immigration authorities and will ensure an efficient turnaround of your employee’s visa application.
Employee insurance is a vital aspect of employment in Vietnam. Employers who prioritize providing robust insurance coverage create a supportive and secure work environment, which in turn enhances employee morale and productivity.
Want to stay up to date with the latest labour laws?
Our publications give you a clear overview of key labour law regulations. We cover major tax, labour law, payroll and visa information. It is designed to get you updated at-a-glance!
Please note that all the information listed below are to be used as a general guideline. For more detailed accounts of Vietnam employment laws and regulations, please visit the official governmental websites.
Updated on: November 2025
Contact Us
Get in touch with one of us today to start streamlining your HR processes across Asia & the Middle East.
