Personal Income Tax
- Malaysian/Resident Employees
- Stay more than 182 days in a calendar year
- Progressive tax rate (0 – 30%)
- Non resident employees
- Stay less than 182 days in calendar year
- Fixed Tax Rate (30%)
Income Tax Table 2025
| Chargeable Income (RM) | Calculations (RM) | Rate % | Tax (RM) |
|---|---|---|---|
| 0 – 5,000 | On the first 5,000 | 0 | 0 |
| 5,001 – 20,000 | On the first 5,000 | 0 | |
| Next 15,000 | 1 | 150 | |
| 20,001 – 35,000 | On the first 20,000 | 150 | |
| Next 15,000 | 3 | 450 | |
| 35,001 – 50,000 | On the first 35,000 | 600 | |
| Next 15,000 | 6 | 900 | |
| 50,001 – 70,000 | On the first 50,000 | 1500 | |
| Next 20,000 | 11 | 2200 | |
| 70,001 – 100,000 | On the first 70,000 | 3700 | |
| Next 30,000 | 19 | 5700 | |
| 100,001 – 400,000 | On the first 100,000 | 9400 | |
| Next 300,000 | 25 | 75000 | |
| 400,001 – 600,000 | On the first 400,000 | 84400 | |
| Next 200,000 | 26 | 52000 | |
| 600,001 – 2,000,000 | On the first 600,000 | 136400 | |
| Next 1,400,000 | 28 | 392000 | |
| Exceeding 2,000,000 | On the first 2,000,000 | 528400 | |
| Public Holiday – all ordinary hours | Every next ringgit | 30 |
Taxable Treatment – New Hire
Form CP22 – Notification of new employees under Section 83(2) of the Income Tax Act 1967.
The Employer must submit the form within 30 days from the commencement of employment. If failed, would be liable to a fine of not less than RM 200 and not more than RM 20,000 or to imprisonment not exceeding 6 months or both. The employer is also responsible for any tax due to the above mentioned.
The notification CP 22 form can be submitted:
Through the e-CP22 application (encouraged) on the MyTax portal; or to the IRB office that handles the employer’s file or any nearby IRB office.
Tax Treatment – Termination/Cessation of Employment
The table below is a general guide for employers to determine whether forms CP22A / CP22B notification is required to be submitted:

Based on the table above, employers are required to submit Form CP22A / CP22B through e-SPC for termination cases that subject for tax clearance.
Tax Treatment – Termination/Cessation of Employment – Leaving country for more than 3 months
The employer is required to withhold any monies payable to an employee who is about to leave Malaysia for a period of more than 3 months with no intention of returning. The employer shall not pay any such money, except with the permission of the IRBM, to or for the benefit of the employee until 90 days after the receipt by the IRBM of the form.
The table below is a general guide for employers to determine whether forms CP21 notification is required to be submitted:
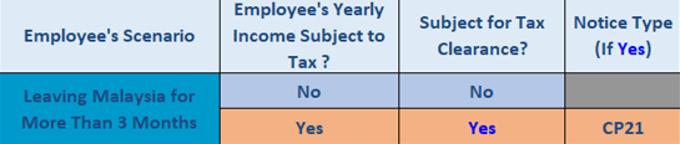
From 1 January 2024, Form CP22A / CP21 is mandatory to be submitted online through MyTax portal using e-SPC application. To expedite the tax clearance process, the employer or employee may visit the IRBM office which handles the employee’s income tax number after submitting the online CP22A or CP21.
Annual Returns Declaration
Employers must submit Form E by March 31st of the following year, declaring the annual returns of all employees. This ensures compliance with income tax regulations and maintains financial transparency.
New Hires Compliance
Employers must submit Form CP22 within one month of a new employee’s start date. Failure to comply may result in fines, imprisonment, and the obligation to resolve outstanding taxes promptly.
Effects of Resignation or Termination
When an employee resigns or is terminated, employers must submit Form CP22A to the Inland Revenue Board along with the appropriate taxes. For employees leaving Malaysia permanently or for more than three months, Form CP21 must also be submitted.
Compliance and Best Practices
Understanding and following monthly deductions, annual income tax rates, and procedures for new hires or terminations are crucial for tax compliance. Both employers and employees must adhere to these regulations to avoid penalties and maintain a robust tax system.
We Provide Expertise on Work Visa Applications!
Our professional team of 200+ has years of experience dealing with local immigration authorities and will ensure an efficient turnaround of your employee’s visa application.
Navigating taxation in Malaysia involves understanding various tax obligations and ensuring compliance. By staying informed and following the correct procedures, employers and employees can contribute to a transparent and effective tax system.
Want to stay up to date with the latest labour laws?
Our publications give you a clear overview of key labour law regulations. We cover major tax, labour law, payroll and visa information. It is designed to get you updated at-a-glance!
Please note that all the information listed below are to be used as a general guideline. For more detailed accounts of Malaysia employment laws and regulations, please visit the official governmental websites.
Updated on: March 2025
Contact Us
Get in touch with one of us today to start streamlining your HR processes across Asia & the Middle East.
